Understanding Home Construction Costs: The Real Price Behind ₹1,800/sq ft
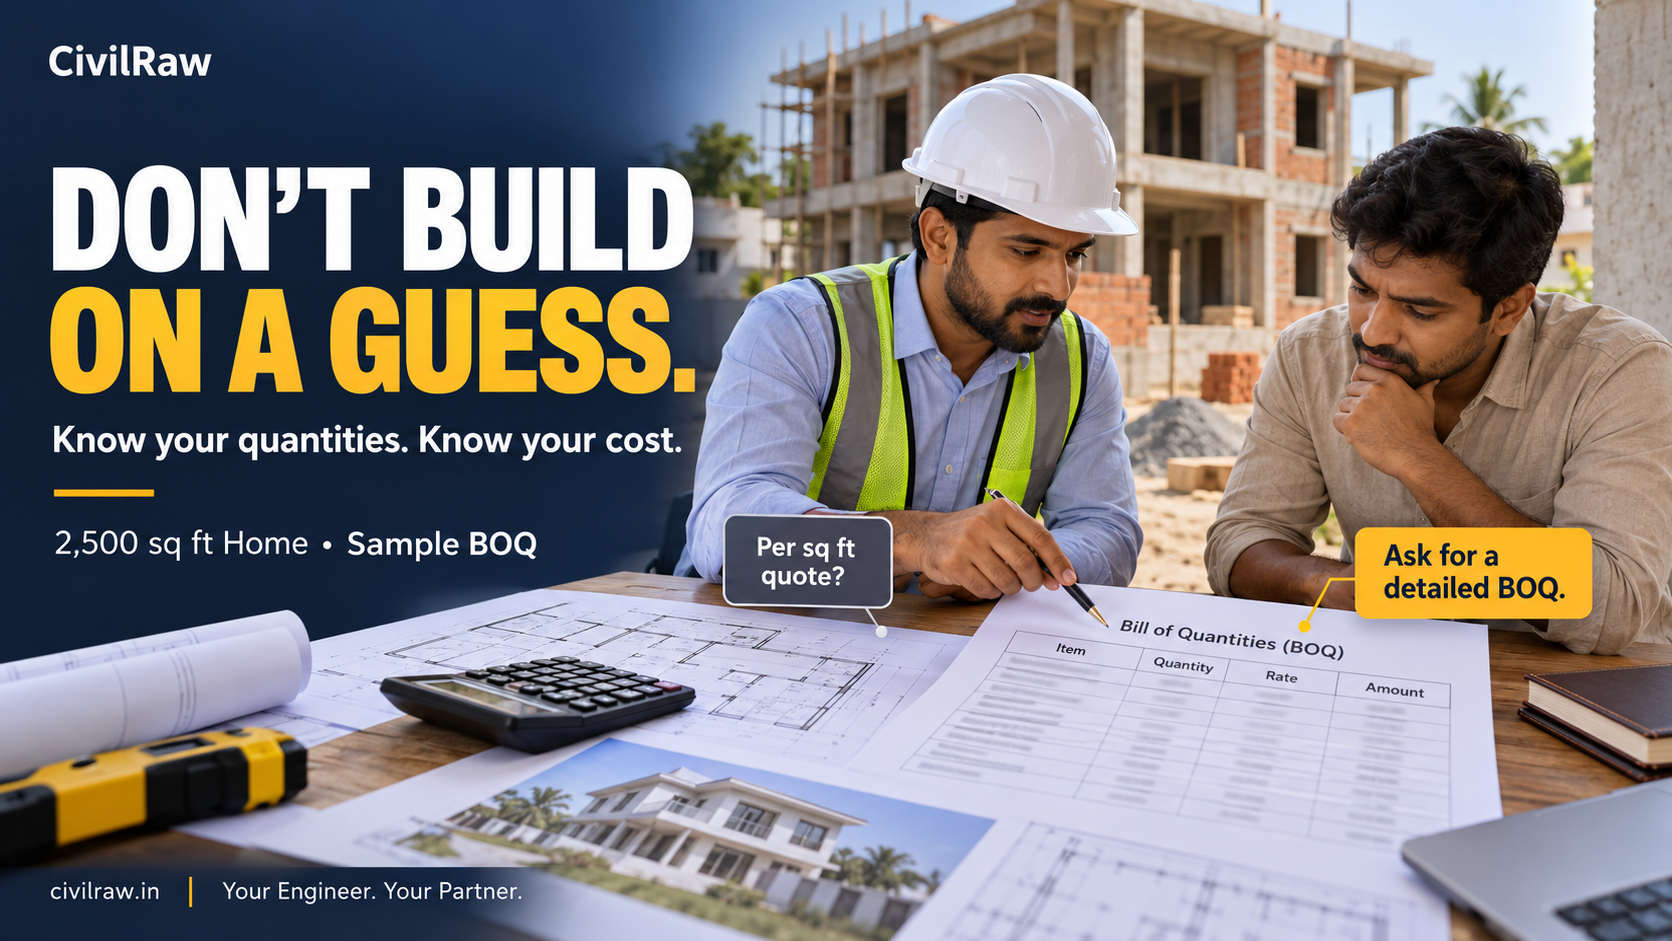
“We will build your house for ₹1,800 per sq ft.”
It sounds simple. Multiply the house area by the quoted rate, and your budget appears ready. For a 2,500 sq ft house: 2,500 × ₹1,800 = ₹45,00,000.
But what exactly does that ₹45 lakh include? Which foundation? How much reinforcement? How many bathrooms? Which windows? What tile allowance? Are waterproofing, railings, electrical fittings and external works included? Without those answers, the quotation is an incomplete basis for a major investment.
Per-square-foot pricing is not automatically fraud. However, an attractive rate can mislead homeowners when quantities, specifications, measurement rules and exclusions remain unclear.
A better approach is to prepare a drawing-based Bill of Quantities, or BOQ, and calculate the cost item by item.
Why One Rate Cannot Explain Your Entire House
| Both houses measure 2,500 sq ft | House A | House B |
|---|---|---|
| Layout | Simple rectangular arrangement | Multiple projections and complex spaces |
| Bathrooms | Three | Five |
| Windows | Moderate window area | Large glazed openings |
| Foundation conditions | Relatively straightforward | Conditions requiring additional work |
| Floor heights | Conventional | Higher floors or double-height areas |
| Finishes | Defined economical selections | Higher-value finishes and fittings |
The quantities and specifications change, so the costs change. A single floor-area figure does not reveal those differences. Floor area describes the size of the building. A BOQ describes the work required to build it.
How a Low Per-Sq-Ft Quote Can Become Expensive
Consider a quotation that promises construction at a low rate but leaves statements such as “standard electrical points,” “basic sanitary fittings,” “normal foundation,” “good-quality tiles,” “doors included” and “extra work charged separately” undefined.
Each phrase leaves room for a different interpretation. Later, additional excavation, extra electrical points, larger windows, selected fixtures or waterproofing details may attract additional charges.
The problem is the gap between what the homeowner expects and what the contract actually includes. A detailed BOQ helps expose that gap before construction begins.
What Is a BOQ?
A Bill of Quantities lists construction activities with their descriptions, units and quantities. When unit rates and amounts are added, it becomes a priced BOQ.
Measured quantity × Agreed unit rate = Item amount
For example: 180 m³ excavation × ₹450/m³ = ₹81,000.
- The activity being priced.
- The quantity allowed.
- The measurement unit.
- The rate applied.
- The resulting amount.
A complete estimate also needs specifications, measurement rules, inclusions, exclusions and commercial terms.
Sample BOQ for a 2,500 Sq Ft House
These are assumed quantities and illustrative budgeting rates—not a measured BOQ, current supplier quotations or a CivilRaw offer. Actual quantities must be taken from architectural, structural and services drawings. Rates must be obtained for the project’s location, specifications and purchasing arrangements.
| Parameter | Sample assumption |
|---|---|
| Total built-up area | 2,500 sq ft, approximately 232.26 m² |
| Building arrangement | G+1, approximately 1,250 sq ft per floor |
| Structural system | RCC frame with masonry infill |
| Bathrooms | Four |
| Roof footprint | Approximately 116.13 m² before measurement adjustments |
| Basement | Not included |
| Foundation | Assumed conventional foundation; subject to design and soil investigation |
| Finishes | Illustrative mid-range selections |
| Land | Excluded |
| Taxes | Excluded; treatment to be established in actual quotations |
The sample terrace waterproofing quantity includes an assumed allowance for detailing and upturns. Flooring, stair finishes and skirting are shown separately.
The concrete and steel quantities below must never be used to design the structure or order materials without drawing-based verification.
A. Preliminary Works and Earthwork
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 1 | Temporary site setup and protection | LS | 1 | ₹50,000 | ₹50,000 |
| 2 | Ordinary-soil excavation | m³ | 180 | ₹450 | ₹81,000 |
| 3 | Backfilling using suitable available excavated material, including compaction | m³ | 120 | ₹300 | ₹36,000 |
| 4 | Surplus excavated material disposal, assumed lead and access | m³ | 60 | ₹650 | ₹39,000 |
| Subtotal | ₹2,06,000 |
Clarify rock excavation, groundwater, imported filling material, disposal distance and access restrictions. Excavation quantities should be built up from foundation pits, trenches and other excavations, not inferred from built-up area alone.
B. Concrete, Reinforcement and Formwork
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 5 | PCC below foundations and other specified locations | m³ | 18 | ₹6,500 | ₹1,17,000 |
| 6 | RCC in foundations, columns, beams, slabs and stairs; excluding reinforcement and formwork | m³ | 125 | ₹7,800 | ₹9,75,000 |
| 7 | Reinforcement supply, cutting, bending and fixing | kg | 12,500 | ₹78 | ₹9,75,000 |
| 8 | Formwork and staging, measured by concrete contact area | m² | 900 | ₹650 | ₹5,85,000 |
| Subtotal | ₹26,52,000 |
This section separates concrete, reinforcement and formwork. If a concrete rate already includes reinforcement and formwork, adding them again would double-count the cost. A tender-ready BOQ should divide these rows by concrete grade, structural element, reinforcement specification and formwork conditions.
C. Masonry and Plastering
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 9 | Masonry, including material and laying; simplified combined allowance | m³ | 125 | ₹6,800 | ₹8,50,000 |
| 10 | Internal wall plastering | m² | 900 | ₹280 | ₹2,52,000 |
| 11 | External wall plastering | m² | 300 | ₹350 | ₹1,05,000 |
| 12 | Ceiling plaster or specified surface finish | m² | 230 | ₹240 | ₹55,200 |
| Subtotal | ₹12,62,200 |
A real masonry BOQ should separate materials and wall thicknesses. Wall volume = wall length × wall height × wall thickness, with deductions following the agreed measurement method. Plastering is measured from actual surface areas, not floor area.
D. Waterproofing
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 13 | Wet-area waterproofing, including assumed upturns | m² | 65 | ₹850 | ₹55,250 |
| 14 | Terrace waterproofing, including assumed detailing allowance | m² | 125 | ₹750 | ₹93,750 |
| Subtotal | ₹1,49,000 |
Specify the system, substrate preparation, junction treatment, protection and testing. Allocate screeds and protective layers clearly so they are neither omitted nor counted under multiple items.
E. Flooring, Wall Tiles and Stair Finishes
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 15 | Floor tiles, supply and installation | m² | 210 | ₹1,600 | ₹3,36,000 |
| 16 | Bathroom and kitchen wall tiles, supply and installation | m² | 100 | ₹1,500 | ₹1,50,000 |
| 17 | Skirting, specified height | running m | 180 | ₹250 | ₹45,000 |
| 18 | Stair stone finishes, measured finished surface area | m² | 35 | ₹2,500 | ₹87,500 |
| Subtotal | ₹6,18,500 |
A supply-and-installation rate differs from a tile purchase allowance. Identify tile size, purchase allowance, installation materials, grout and finishing details. State how cutting and procurement wastage are treated; avoid charging the same allowance twice.
F. Doors, Windows and Railings
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 19 | Main entrance door set, including specified frame and hardware | set | 1 | ₹65,000 | ₹65,000 |
| 20 | Internal door sets | set | 8 | ₹14,000 | ₹1,12,000 |
| 21 | Toilet door sets | set | 4 | ₹9,000 | ₹36,000 |
| 22 | Windows, including assumed glazing and hardware | m² | 30 | ₹6,500 | ₹1,95,000 |
| 23 | Railings, assumed height and specification | running m | 25 | ₹4,200 | ₹1,05,000 |
| Subtotal | ₹5,13,000 |
Attach door and window schedules with sizes, materials, sections, glazing, finishes and hardware. A single window rate is not meaningful without a window specification.
G. Painting
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 24 | Internal wall and ceiling painting system | m² | 1,130 | ₹180 | ₹2,03,400 |
| 25 | External painting system | m² | 300 | ₹220 | ₹66,000 |
| Subtotal | ₹2,69,400 |
Define surface preparation, putty where required, primer, paint product and application system. Reconcile painting quantities with tiled walls and surfaces receiving other finishes.
H. Electrical, Plumbing and Completion
| No. | Description | Unit | Assumed quantity | Sample rate | Amount |
|---|---|---|---|---|---|
| 26 | Typical electrical wiring points, including assumed conduits, wiring and switches | point | 100 | ₹1,400 | ₹1,40,000 |
| 27 | Distribution boards, protection and earthing provision | provisional sum | 1 | ₹85,000 | ₹85,000 |
| 28 | Bathroom water supply and drainage rough-in | bathroom set | 4 | ₹35,000 | ₹1,40,000 |
| 29 | Bathroom sanitary fixtures and fittings | bathroom set | 4 | ₹30,000 | ₹1,20,000 |
| 30 | Kitchen and utility plumbing | provisional sum | 1 | ₹40,000 | ₹40,000 |
| 31 | Final testing coordination and cleaning, excluding separately specified laboratory tests | LS | 1 | ₹35,000 | ₹35,000 |
| Subtotal | ₹5,60,000 |
Replace services allowances with circuit schedules, point categories, pipe lengths, diameters, fittings and fixture schedules in a detailed BOQ. Price high-load circuits separately where requirements differ. A provisional sum is a placeholder requiring later definition; it does not provide the certainty of a fully measured item.
Sample BOQ Cost Summary
| Work section | Amount |
|---|---|
| A. Preliminary Works and Earthwork | ₹2,06,000 |
| B. Concrete, Reinforcement and Formwork | ₹26,52,000 |
| C. Masonry and Plastering | ₹12,62,200 |
| D. Waterproofing | ₹1,49,000 |
| E. Flooring, Wall Tiles and Stair Finishes | ₹6,18,500 |
| F. Doors, Windows and Railings | ₹5,13,000 |
| G. Painting | ₹2,69,400 |
| H. Electrical, Plumbing and Completion | ₹5,60,000 |
| Direct-work subtotal | ₹62,30,100 |
| Illustrative contractor overhead and profit: 8% | ₹4,98,408 |
| Estimated works value before taxes | ₹67,28,508 |
| Owner’s contingency: 10% of estimated works value, rounded | ₹6,72,851 |
| Illustrative funding provision before taxes and exclusions | ₹74,01,359 |
The unit rates above are assumed to exclude the separately added contractor overhead and profit. Establish whether these are already included before adding another percentage. The contingency is an owner’s reserve, not automatically payable to the contractor.
This total is the result of this particular sample—not a market price for every 2,500 sq ft house in Hyderabad.
What This Sample Excludes
- Land and acquisition costs.
- Architectural, structural and services design fees.
- Survey, soil investigation and permissions.
- Rock excavation, dewatering and special foundations.
- Compound wall, main gate and external paving.
- Sump, tanks, borewell, pumps and external utility connections.
- Lift, solar, backup systems and air-conditioning equipment.
- Modular kitchen, wardrobes, false ceilings and furniture.
- Appliances, decorative lighting and specialist systems.
- Applicable taxes.
A project BOQ must also capture design-specific items such as lintels, parapets, sills, roof drainage and elevation features within clearly identified rows.
The Right Time to Calculate Per-Sq-Ft Cost
After preparing the BOQ, an equivalent rate can help summarise or compare the estimate.
₹67,28,508 ÷ 2,500 sq ft = approximately ₹2,691 per sq ft.
That figure excludes contingency, taxes and the listed exclusions. The per-sq-ft figure is an output of the estimate. Quantities and specifications explain how it was reached. This is more informative than selecting an attractive rate first and discovering missing scope later.
A BOQ Also Makes Changes Easier to Understand
Suppose approved additional work requires 10 m² of the same specified window system × ₹6,500/m² = ₹65,000.
The change can be priced against the agreed measurement and rate, subject to the contract’s treatment of overheads, taxes and associated work. The homeowner can see what changed and why the amount changed.
What Homeowners Should Request Before Signing
- Detailed scope of work Agreement
- Coordinated drawings with revision numbers.
- A measured BOQ.
- Written material and workmanship specifications.
- Clear rate inclusions and exclusions.
- Agreed measurement rules.
- Payment milestones or measured-work billing arrangements.
- A written variation approval process.
- A construction schedule.
- Inspection and testing responsibilities.
- Clear treatment of taxes, overheads and price changes.
A BOQ improves transparency, but its accuracy depends on complete drawings, correct measurements and realistic rates.
Frequently Asked Questions
Is per-sq-ft construction pricing a fraud?
Not automatically. It can be a useful summary when scope, specifications and measurement rules are clear. It becomes misleading when a low rate conceals important exclusions or undefined allowances.
Why is BOQ-based costing better?
It shows the activities, quantities, rates and amounts behind the budget. This makes quotations, changes and progress payments easier to review.
Can an exact BOQ be prepared from 2,500 sq ft alone?
No. Built-up area alone does not establish excavation, concrete, steel, walling, finishes or services quantities. Those require drawings and project specifications.
Does a BOQ guarantee the final cost?
No. Design changes, quantity variations, site conditions, procurement prices and contract terms can affect the final amount. Updating the BOQ and change register helps maintain control.
Can I use this sample to order construction materials?
No. It illustrates the costing process. Material orders require verified quantities, approved drawings and appropriate procurement allowances.
Get Your House Costed From Drawings
Before asking, “What is your rate per sq ft?”, ask: “What work is included, how much is required, and how has each item been priced?”
CivilRaw supports homeowners in Hyderabad with BOQ preparation and verification, quotation comparisons, budget monitoring, measurement reviews and independent quality inspections.
Share your drawings, site location, proposed floors and specifications to discuss a project-specific costing exercise.
CivilRaw — Your Engineer. Your Partner.
Planning Your Construction?
Don't rely on guesswork. Get a transparent, engineer-backed estimate for your home.
Get Cost Estimate